
Importing a supercar into the UK involves more than agreeing a price and booking a transporter. Between the point of purchase abroad and turning the key on a British road, a car must pass through customs, HMRC and the DVLA – and each stage has its own paperwork, deadlines and, in some cases, its own bill.
For collectors, however, there is one particularly important decision to make before the car is shipped. If the vehicle is brought directly into an HMRC-authorised customs warehouse rather than released into UK free circulation, customs duty and import VAT can remain suspended while it stays under the procedure. For a six- or seven-figure car, this can materially affect the financial decision about when – or whether – to register it in Great Britain at all.
This article principally covers vehicles imported into Great Britain: England, Scotland and Wales. Different customs and VAT rules may apply to vehicles imported into Northern Ireland.
Importing a supercar into Great Britain: the short version
A vehicle imported permanently into Great Britain may be subject to customs duty and 20% import VAT. HMRC must normally be notified through NOVA, and the vehicle may require approval before it can be registered with the DVLA. If it is instead imported directly into an HMRC-authorised customs warehouse, duty and import VAT can remain suspended while it is stored. If the vehicle is subsequently re-exported without being released into UK free circulation, those suspended UK import charges will generally not become payable.
What does it actually take to import a supercar into Great Britain?

For a conventional permanent import, the process normally involves six principal stages:
1. Purchase, acquisition or ownership documentation
2. Shipping and the customs declaration
3. Payment of duty and import VAT – or entry into customs warehousing
4. Notification to HMRC through NOVA
5. Vehicle approval, where required
6. DVLA registration, vehicle tax and insurance
None of these stages is necessarily difficult in isolation. What catches owners out is the sequencing.
The DVLA will not register an imported vehicle until the NOVA position has been processed, any duty and import VAT required for release into free circulation have been dealt with, and the appropriate evidence of vehicle approval has been obtained.
A supercar or important classic will also usually require a level of care during transport, customs clearance and storage that would not be necessary for a routine vehicle import. Planning the customs and storage route before collection is therefore particularly important.
How much duty and VAT will you pay to import a car into Great Britain?

The amount payable depends on the vehicle, its customs classification, its origin, where it is being imported from and whether any relief or preferential rate applies. For many passenger cars imported from outside the UK, a typical starting point is 10% customs duty, followed by import VAT at 20%.
Duty is calculated using the vehicle’s customs value, which may include transport and insurance costs up to the relevant UK border point. Import VAT is then calculated using a value that includes the customs value, customs duty and certain delivery or incidental costs. As a simplified illustration, if a vehicle has a customs value of £200,000 and attracts 10% duty, the duty would be £20,000. Import VAT at 20% on £220,000 would then be £44,000 – a combined duty and VAT bill of £64,000.
In practice, shipping, insurance and other chargeable costs may increase the final figure. This is precisely why customs warehousing is worth considering before a vehicle is shipped, rather than after it arrives.
Two preferential routes are also worth understanding, although neither applies automatically.
A vehicle that qualifies as EU-originating under the UK-EU Trade and Cooperation Agreement may qualify for 0% customs duty, provided the applicable rules of origin are satisfied and the preferential claim is supported by the required evidence. Simply buying a car in an EU country does not make it EU-originating. A US-built vehicle purchased from a dealer in Germany, for example, will not ordinarily become EU-originating merely because it was purchased there.
Preferential rates may also apply to vehicles originating in other countries with which the UK has an applicable trade agreement, including Japan. The precise rate, origin requirements and supporting evidence should always be checked against the current UK tariff before shipment.
Vehicles that qualify as historic or collectors’ items may also receive different customs-duty and import-VAT treatment. Qualification depends on the vehicle’s precise classification, age, characteristics and documented history, so it should be confirmed with a suitably experienced customs agent rather than assumed.
What is NOVA, and why does the 14-day deadline matter?

NOVA – the Notification of Vehicle Arrivals system – is how HMRC is notified about a vehicle brought permanently into the UK. HMRC must normally be notified within 14 days of the vehicle’s arrival, and the DVLA will not register it until the NOVA notification has been processed. A late notification may result in a penalty.
For valuable or unusual vehicles, it is sensible to gather the supporting documents before the car is shipped. Depending on the circumstances, HMRC may require:
- The customs declaration or Movement Reference Number
- The invoice or bill of sale, if the vehicle was bought within the previous six months
- A current valuation if it was bought more than six months ago
- An official document confirming the VIN or chassis number
- Evidence supporting any claim for customs relief or preferential origin
Where a current valuation is required, HMRC states that it must be undertaken in person in the UK by a garage, dealership or other recognised business.
The NOVA and customs arrangements for a vehicle entering customs warehousing should be structured with the customs agent from the outset. A warehoused vehicle will not proceed to DVLA registration while it remains under the procedure; the relevant NOVA, duty, approval and registration steps must be coordinated if the owner later decides to release it into free circulation for permanent UK use.
Does an imported supercar need UK vehicle approval before it can be driven?
Many imported vehicles require evidence that they meet the applicable environmental and safety standards before they can be registered and taxed.
The correct route depends principally on the vehicle’s age, previous registration and approval status.
A vehicle first registered or manufactured more than ten years ago may be exempt from the normal vehicle-approval requirement, although you should confirm this for the particular car. For newer vehicles, an EU-registered car may be supported by a European Certificate of Conformity. If it is left-hand drive, it may also require a GB conversion Individual Vehicle Approval certificate. A vehicle that was not registered in the EU will commonly require Individual Vehicle Approval, known as IVA. Modifications may be needed before it can pass, including changes to lighting, speedometer displays and other equipment.
The correct approval route should ideally be established before the vehicle arrives, particularly for a limited-production supercar or a model that was never officially supplied in the UK.
What is an HMRC customs warehouse, and how does it change the numbers?

A customs warehouse – often described as bonded storage – is a facility authorised by HMRC to hold imported goods under customs control without customs duty and import VAT becoming immediately payable.
There is generally no fixed statutory storage period, provided the vehicle remains correctly entered under the customs warehousing procedure and all the conditions of the warehouse authorisation continue to be met.
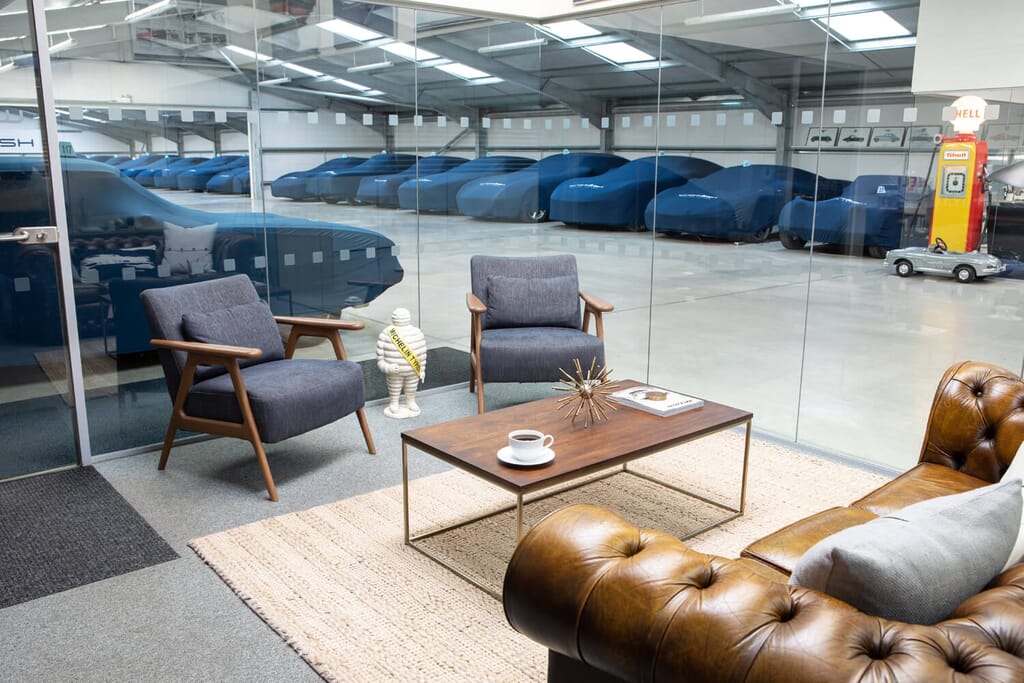
Both Windrush storage sites, in London and the Cotswolds, hold this authorisation.
Duty and import VAT remain suspended while the car stays under the procedure. If it is subsequently released into UK free circulation—typically so that it can be registered and used on British roads – the applicable duty and import VAT become payable at that point.
If the vehicle is instead re-exported directly from customs warehousing without being released into free circulation, the suspended UK import charges will generally not become payable.
While under customs warehousing, the vehicle remains subject to customs control. It cannot ordinarily be driven, used privately or removed from the authorised arrangements unless the appropriate customs procedure and documentation have first been completed.
Customs warehousing is particularly useful for an owner who has bought a vehicle abroad but has not yet decided whether to:
- Register and use it in Great Britain
- Hold it as part of a collection
- Sell it to another collector
- Re-export it to another country
It keeps those options open without requiring the owner to pay the full UK duty and import-VAT bill immediately.
The customs declaration and subsequent release, NOVA and registration processes must be structured correctly. This is why the warehousing route should be arranged before the vehicle reaches the UK, rather than decided retrospectively.
How does Windrush help with importing and storing a supercar?

For a vehicle being acquired abroad and brought into Great Britain, the practical value of working with Windrush lies in joining together the different stages of the process. Working with specialist freight and customs partners, we can help coordinate collection and enclosed transportation, customs documentation and the vehicle’s arrival directly into our authorised customs warehouse.
Receiving the vehicle into the correct procedure from the outset protects its customs position and prevents inadvertent release into free circulation. If the owner later decides to register and use the car in Great Britain, we can help coordinate the necessary customs release, NOVA, vehicle approval and DVLA registration processes with the relevant specialists. Alternatively, if the vehicle is intended to remain as an unregistered collection asset, it can continue to be stored and cared for under customs warehousing, subject to the requirements of the procedure and the warehouse authorisation.
If you are considering importing a supercar into the UK – or already have one awaiting shipment – speak to Windrush before it leaves its current home. The earlier the transport, customs and storage route is planned, the more options remain available when the car arrives.
Frequently asked questions on Importing a Supercar
Can I import a car into the UK without paying duty immediately?
Potentially, yes. If the vehicle is correctly entered into an authorised customs warehousing procedure, eligible customs duty and import VAT can remain suspended while it is stored.
Do I pay UK import duty on a car bought in Europe?
Not necessarily. A vehicle that qualifies for preferential origin under the UK-EU Trade and Cooperation Agreement may attract 0% customs duty, provided the relevant rules of origin are met and the claim is supported by the required evidence.
Simply buying a vehicle in an EU country does not establish that it is EU-originating.
Can a bonded car be sold while it is in storage?
Yes. Ownership of goods held in a customs warehouse may change while they remain under the procedure, provided the warehouse records and customs responsibilities are updated correctly.
A change of ownership does not release the vehicle from customs control. Any subsequent removal, release into free circulation or re-export must follow the appropriate customs procedure.
Can I drive a car while it is in bonded storage?
Not ordinarily. A vehicle held under customs warehousing remains under customs control and cannot simply be removed for private use. Any temporary removal or use would require prior confirmation that an appropriate customs procedure has been completed.
What happens if the car is exported again?
If the vehicle is re-exported directly from customs warehousing without first being released into UK free circulation, the suspended UK customs duty and import VAT will generally not become payable.